Buying a car
USAA Used Car Loan Rates: Advertised APR vs. Your Actual Offer
Compare USAA’s dated advertised APR with your actual used-car offer, including dealer versus private-sale terms, discounts, loan length and total payments.
Published
Sources checked . How this guide is prepared.
START HERE
The short answer
USAA does not offer one rate that applies to every used-car borrower. On November 21, 2026, its public auto-loan page advertised purchase loans as low as 4.49% APR, including an optional automatic-payment discount. That is a general advertised floor, not a verified offer for your used car or private-party purchase.
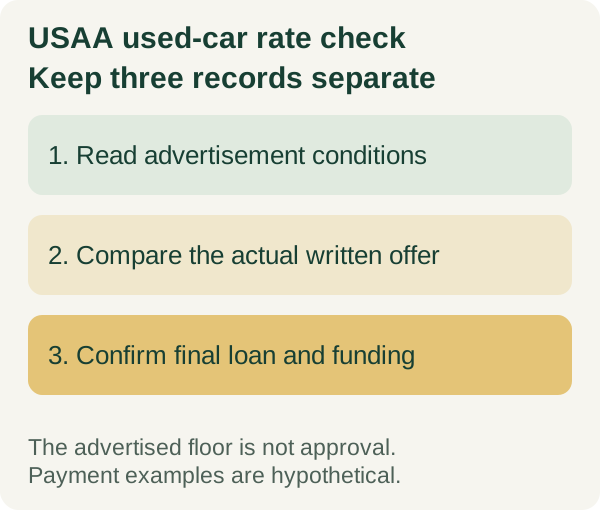
Check the live rate and its conditions, then compare your actual written offer for the same vehicle, amount and term. CarTruvo does not issue USAA loans, determine membership or credit eligibility, or obtain a personalized rate through this guide.
What the advertised 4.49% APR actually establishes
USAA’s official auto-loan page displayed that general purchase-loan headline when checked in Safari. Its rate footnote describes the lowest displayed APRs as applying to 36-month terms, dealer purchases and refinancing, with a 0.25% discount for optional automatic payments.
The footnote says rates vary with approved credit and factors including term, model year, amount and loan purpose. Rates and terms can change. Do not label the headline as a guaranteed used-car rate, a private-seller rate or an offer for a longer term.
Use the current official page when you shop. Record the date, loan purpose and conditions beside the advertised number. A dated rate observation is useful context, but your actual financing decision needs an eligible offer for your purchase.
Keep three rate records separate
Use three entries: the public advertisement, your actual approval or offer, and the final loan documents. This is an original comparison method, not a substitute for the bank’s disclosures.
For the advertisement, record the headline and footnotes. For your offer, identify the actual borrower and vehicle conditions, amount, APR, term, discount requirements and expiration. For the final documents, confirm that the agreed terms and purchase details still match before signing.
Leave an unanswered field marked unknown. Membership, an illustrative calculator result, an approval and completed funding describe different stages. Ask USAA to explain what remains conditional rather than assuming an early result settles every vehicle and payment detail.
Can a USAA loan be used with a private seller?
USAA’s auto-loan FAQ says private-party purchases can be financed. It describes finalization using the VIN, odometer reading, seller details and final amount, followed by required documents and a seller-payable check with title-transfer instructions.
That purchase route does not establish that the general advertised dealer/refinance floor applies. Ask the bank for the rate, eligible vehicle, payment process and timing for your actual private sale. Resolve any existing lien or title issue before arranging the handoff.
Use the private-party auto loan guide for the wider purchase sequence. Confirm the actual lender instructions instead of treating an article or a seller’s preferred payment method as funding authorization.
What should you confirm before choosing a term?
USAA’s public page makes longer terms conditional on approved credit, amount and vehicle criteria. Ask which terms are available for your actual car and loan. A maximum term shown in marketing does not mean every vehicle or amount qualifies.
Give competing lenders the same purchase price, down payment and requested amount. Ask each for the APR, payment schedule, complete borrowing costs and any conditions attached to a discount. Keep optional products and ownership expenses visible rather than fitting everything to a desired monthly payment.
The CFPB’s loan-comparison guidance recommends comparing amount financed, APR and interest rate, term and payment. It explains why a longer repayment period can lower the payment while increasing the total cost.
An original payment-schedule comparison
Imagine two invented schedules for the same assumed $20,000 amount borrowed. Offer A has 60 payments of $420, totaling $25,200. Offer B has 72 payments of $365, totaling $26,280.
B is $55 less each month, lasts 12 months longer and totals $1,080 more in scheduled payments. These figures are not USAA quotes. The illustration does not calculate either APR or account for additional charges, timing changes or early payoff.
Use the arithmetic as a check on actual documents, then compare the APRs and complete terms. A lower payment alone does not establish the lower-cost offer or tell you whether the loan fits your situation.
Confirm discount conditions and the offer window
USAA’s FAQ explains conditions for its optional automatic-payment discount, including setup before signing and ownership verification when using an external account. It also describes a 45-day period to finalize an approved loan and purchase the car.
Confirm the dates and repayment arrangement in your own offer. Ask what happens if the vehicle, amount or planned purchase date changes. Do not infer that a calculator estimate is locked for that period or that every later change preserves the same terms.
For a broader ownership budget, the car-financing guide separates purchase price, add-ons and borrowing costs. Insurance, registration, maintenance and repair planning remain part of affording the car after the loan payment is chosen.
Download the USAA rate-and-offer worksheet
The blank USAA used-car loan comparison worksheet records sixteen advertisement, eligibility, vehicle, APR, term and funding questions. Use it alongside the actual offer and a comparable alternative.
Source check: November 21, 2026. The 4.49% figure is a dated observation of USAA’s general public purchase-loan advertisement, not a used-car approval or continuing rate promise. No application, credit inquiry, personal quote or independent financial-professional review was performed for this guide.
BEFORE YOU TAKE THE NEXT STEP
Practical checklist
Check the VIN, ownership record and seller details.
Arrange an independent inspection and review the written terms.
Confirm the total cost and title-transfer process before paying.
CHECK THE DETAILS
Sources and further reading
Follow the source linked beside a claim for its context. For a transaction, confirm current requirements with the relevant agency, lender or provider.
- USAA’s official auto-loan pageusaa.com
- USAA’s auto-loan FAQusaa.com
- The CFPB’s loan-comparison guidanceconsumerfinance.gov
YOUR NEXT READ